
A fund admin is one of the most important service providers for a VC. Here’s my take on the best admins for venture funds in the $10M-$100M range, based on my experience as fund counsel for more than 50 emerging VCs, and conversations with many more.
But before I jump in, please subscribe for more highly practical content about launching and running a venture fund:
Here’s what’s in this post:
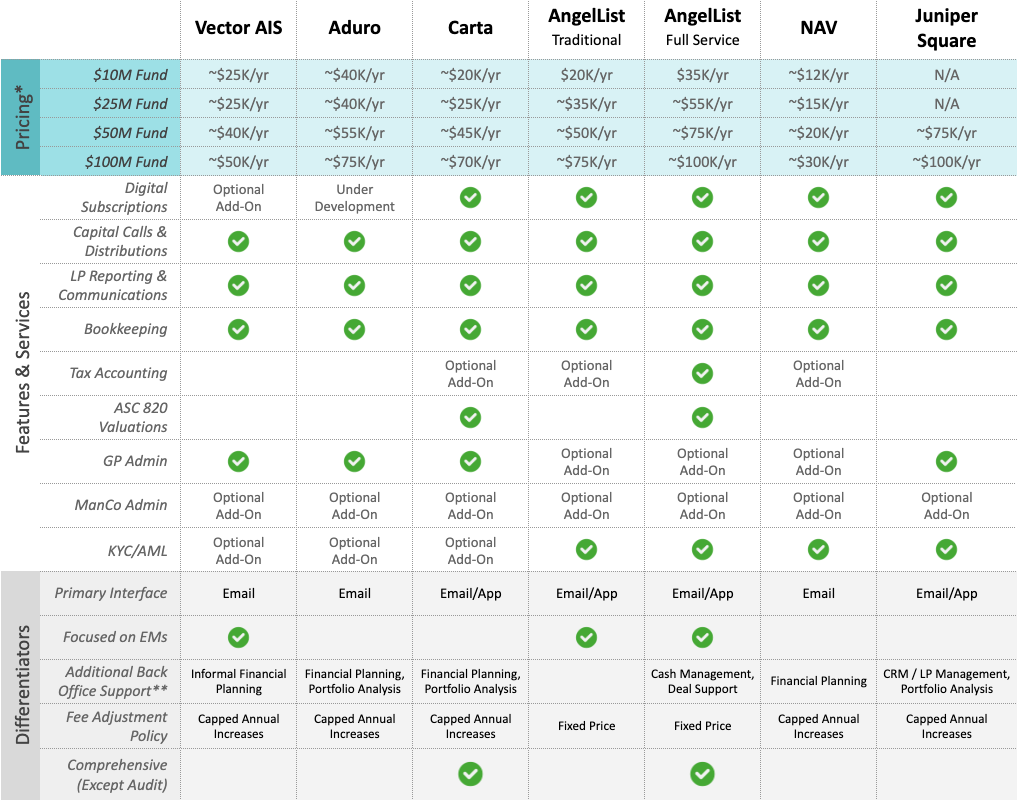
The master comparison chart
What does a fund admin do?
There are three core services that every fund admin will provide:
Internal Accounting / Bookkeeping: The most basic function of a fund admin is to prepare the fund’s books and records, track the fund’s transactions, and make sure that each limited partner (LP)’s interest is properly recorded, and the fund’s income and expenses are correctly allocated to each LP. This internal accounting is like ordinary book-keeping, but it needs to strictly follow the rules laid out in your fund documents to avoid serious consequences from LPs and the SEC.
Capital Calls & Distributions: Every fund admin will oversee your fund’s capital calls and distributions. That means calculating each LP’s portion of the capital call or distribution, sending the appropriate notices to those LPs, making sure that the money has actually changed hands, and reflecting the transaction in the fund’s books and records.
LP Reporting & Communications: Every fund admin will provide some sort of reporting to your LPs regarding the fund’s finances and the value of the fund’s portfolio. This is often done through a combination of an annual financial statement and an online LP dashboard which provides real-time views of the value of each LPs’ interest in the fund, their remaining capital commitment, and other key information. In addition to this reporting, fund admins distribute notices, amendments and other formal communications to the fund’s LP-base.
Many fund admins go beyond that core set of services, and try to act more like a comprehensive back-office for their clients with the following:
Digital Subscriptions: Some fund admins will provide a platform that allows you to admit LPs into the fund (i.e. “close” the LPs) by uploading fund documents, gathering key information and signatures from LPs, and gathering counter-signatures from the general partner (GP) of the fund. These fund admins will often also handle key LP diligence - known as KYC/AML (know your customer/anti-money laundering). This is a very valuable service because funds often have dozens to hundreds of LPs, and shuffling this paper and performing the diligence can be very labor intensive. Fund admins who do not handle closings often refer out to Passthrough - a streamlined and simple closing platform that often charges ~$5,000 per fund, plus additional fees for KYC/AML services.
Taxes: While every fund admin will handle your fund’s internal accounting, only some will prepare the fund’s tax return and K-1s. Fund admins who do not handle tax accounting often have close relationships with accounting firms that frequently work with emerging VCs, such as Andersen (which handles taxes but not audit), Frank Rimerman, Sensiba, and Weaver. Hiring a third-party accounting firm to prepare the fund’s taxes generally costs $8,000-$15,000 per year.
Valuations: Every fund is required to value its investments at least annually using a reasonable and consistent valuation policy. While this is generally simple in the early years of the fund (using a “latest round value” method), it can get more complex in the later years of a fund. Some fund admins will perform these valuations for their clients using industry-standard “ASC 820” valuation methods.
GP Admin: Multi-GP entities, or solo-GP entities that share carry with advisers or anchors, will require some administrative work. This mostly entails distributing K-1s, and calculating distributions and capital contributions from the GP entity’s members. If you are a solo-GP who won’t be sharing carry, you do not need this.
Management Company Admin: A Management Company is the entity that contains a venture firm’s brand and operations, and it requires administration like any other small business. This often involves bookkeeping, vendor payments, payroll management, 1099 filings, and earnings distributions to partners. If you are a solo-GP without employees, you likely do not need this.
AML Compliance: While VCs were previously exempted from “anti-money laundering” (AML) compliance, that’s about to change. Upcoming SEC and FinCEN regulations will require emerging VCs to assess the AML risk of their LP-base, adopt policies and procedures to manage that risk, and run regular AML checks on each LP, among other requirements. Some - but not all - fund admins perform AML checks as part of their services, which better positions them to help with these new compliance requirements.
In addition to varying on features and price, fund admins also vary on some softer factors, like the degree of focus small venture funds, price increase policies, staffing policies (e.g. do you get a dedicated team), and additional back-office tools and services (like cash flow planning and portfolio analysis). One soft factor that does not to vary much across options: while all of the admins have developed extensive “platform” apps to help manage your fund, most interactions with your fund admin will likely still occur through email.
What are some popular options for emerging VCs?
There are dozens of fund admins out there, but a few names regularly pop up when it comes to emerging VC funds.
Vector AIS: Vector is a newer fund admin that is focused on funds of all stages, from the emerging manager community to established managers. They offer an experienced team (veterans from other admins), a good balance of human support and technology, and a focus on building close relationships with their clients. They are a “service-first, people-first firm elevated by technology”, with a proprietary platform called Valence. Because the firm is new and growing, it often offers an attractive mix of competitive pricing and top-notch service.
Aduro: Aduro is one of the best known and most established fund admins for emerging VCs. Since 2012, they have worked with, and grown alongside, standout funds like FirstRound and Craft. It’s a trusted and dependable option, that combines a very experienced team with a proprietary platform called FundPanel. Aduro offers a good combination of well-known brand, high-touch support, and well-designed tech.
Carta: Carta is a ubiquitous presence and platform in the venture ecosystem. It has a strong fund admin division that aims to act as a comprehensive back-office, and works with a broad range of fund sizes (from $5M-$1B+ AUM). Carta has an impressive array of add-on features, including a very useful financial planning tool (Carta Fund Forecasting). They also have a uniquely large and multi-national support team (450+ employees).
AngelList (jointly with Belltower): AngelList’s fund admin “full service” option is built to be a comprehensive back-office for emerging VCs. While AngelList is explicitly product-focused and thinks of itself as a software company, the human support at AngelList is actually a great fit for new emerging VCs who need a bit more orientation and help. In addition to their “full service” option (which is a uniquely comprehensive back office service that includes deal support) - AngelList recently rolled out a “traditional” fund admin alternative that is closely comparable to the other fund admins in this list in pricing and features.
NAV: NAV has been in the fund admin business for 30 years and is a professional and competitively priced option for emerging VCs. You can expect efficient service, and significant back office support (including tax preparation and AML/KYC). NAV is also a well-known option for crypto funds, and should be on the list of any emerging VC who is focused on digital assets (especially when a fund will be actively trading crypto in addition to its standard venture investments).
Juniper Square: Juniper Square is an institutional-grade admin for emerging and mid-sized managers ($50M–$100M+) that are planning to scale quickly or form complex vehicles (e.g. evergreen funds). In addition to high-touch fund administration, Juniper Square provides a very well designed platform that centralizes fundraising, LP information, capital activity, and fund data.
Other options to consider
This post has focused on a few of the most popular fund admins for emerging VCs raising funds in the $10M-$100M range. Here are a few other options that might be worth considering:
VeriVend: VeriVend is a combination of a digital subscription platform, a payments platform, and a ledger/accounting platform. In the hands of a manager who really knows what they’re doing, VeriVend can replace a traditional fund admin. With integrated banking and simple capital calls and distributions, VeriVend may be a good, cost-effective option for (1) experienced managers launching standalone SPVs, syndicates, and simple funds and (2) firms with significant legal and finance support that want to self-admin their funds.
Sydecar: Sydecar is a venture-backed, product-focused fund admin that offers turn-key venture fund formation and administration. They’re usually the fastest and least expensive option for VCs looking to form and run very small funds (<$5M in capital commitments).
The shifting landscape (2026 vs. 2025)
Here are some major shifts in the fund admin options for emerging managers over the past year:
AngelList has overhauled its admin pricing and product to appeal to larger and more institutional funds.
While its foundation is still venture, Carta has expanded its focus to private equity, private credit, and real estate, and has begun rolling out features and services aimed at those asset classes.
Standish seems to have shifted its focus away from emerging VCs, despite its acquisition of Cornerstone (an admin focused on the emerging VC market).
Many admins seem to be shifting strategic focus up-market, towards larger funds - it’s becoming more difficult for $10M funds to find admins.
That’s it for this post! You can find out more about our fund formation and fund counsel services on the Lidow PC site. To connect with me about this post or other fund-related questions, you can message me on LinkedIn.
And if you haven’t already, please subscribe for more highly practical posts about forming and managing a venture fund:
Useful comparison for lean Fund I teams picking admin before first close.
One adjacent ops gap we see on the capital-formation side: even with clean admin and dashboards, warm LP paths still stall when the connector has to rewrite the ask. Logging the name is necessary. Finishing a paste-ready forwardable is the other half.
Curious how readers timed admin choice vs active fundraising without losing raise weeks.
Great article . Just sent you a message on LinkedIn